Key takeaway
- Data analytics in insurance for 2027: underwriting, claims, fraud, pricing and retention use cases, agentic AI in claims, and EU AI Act and NAIC rules.
Data analytics in insurance means using policy, claims, customer and third-party data to price risk, settle claims, find fraud and keep profitable customers. In 2026 the work has moved from dashboards that describe last quarter to predictive models and AI agents that act inside underwriting and claims workflows.
That shift brings regulation with it. The EU AI Act lists AI used for risk assessment and pricing in life and health insurance as high-risk, and most US states have adopted the NAIC model bulletin on insurers' use of AI. Analytics leaders now need governance, documentation and human oversight built in from the first model.
What does data analytics in insurance cover going into 2027?
Insurers have always been analytics businesses: actuaries price risk from historical loss data. What has changed is the range of data, the speed of decisions and the move from analysis to action. Most programmes now combine four layers.
| Layer | Question it answers | Typical insurance example |
| Descriptive | What happened? | Loss ratio by product, region and channel |
| Predictive | What is likely to happen? | Probability that a claim is fraudulent or that a policyholder will lapse |
| Prescriptive | What should we do? | Which claims to fast-track, which renewals to offer a retention discount |
| Agentic | Can a system take the next step, within limits? | An AI agent gathers documents, checks coverage and drafts a claim decision for an adjuster to approve |
The data foundation underneath is the same for all four layers: a governed big data platform that joins policy administration, claims, billing, CRM and external sources such as telematics, property and weather data.
Which use cases deliver value first?
The use cases below are the ones most insurers start with, because the data already exists and the business owner is clear.
| Use case | What analytics does | When it fits | Current regulatory status |
| Underwriting and risk assessment | Scores applicants using application, medical, property or telematics data; routes simple cases straight through | High application volumes with repeatable rules | High-risk under EU AI Act Annex III 5(c) when it covers natural persons in life and health insurance |
| Pricing | Builds and compares models of expected cost against risk so premiums match exposure | Competitive markets where price comparison drives switching | Same Annex III 5(c) scope for life and health; in the US, rates built with AI must still be not excessive and not unfairly discriminatory |
| Claims triage and reserving | Predicts severity and final cost, prioritises claims, supports reserves including IBNR | Large claim volumes, long-tail lines | NAIC bulletin: claims decisions must meet unfair claims settlement practices law |
| Fraud detection | Flags suspicious claims and networks so investigators focus where return is highest | Any line with investigation backlogs | India: IRDAI fraud monitoring framework requirements apply from 1 April 2026 (as reported by JSA) |
| Customer retention | Predicts lapse and churn, recommends next best action at renewal | Personal lines and life with renewal cycles | Price-related actions on natural persons may fall under the same fairness rules as pricing |
Underwriting and pricing
Price comparison makes mispricing expensive: the lowest quote can win the business while being underpriced against the risk. Analytics lets underwriters test whether a price is appropriate for the risk before it is offered. For people with existing medical conditions, models built on medical history can help a life insurer or reinsurer decide which applicants can be accepted without a full medical assessment, which widens access while controlling cost. Because these decisions directly affect individuals, they are the area of most regulatory attention.
Claims and reserving
A claim can change a great deal in value between first notice and final payment. Predicting the final cost early improves reserving, including incurred but not reported (IBNR) amounts, and the predicted developed loss for each claim can feed back into pricing models. Severity scores also decide which claims can be paid quickly and which need an adjuster or an inspection.
Fraud
It is too costly to investigate every claim, and investigating honest customers damages trust. Predictive models rank claims by fraud likelihood so investigators spend time where it matters. Network analysis using graph databases helps find rings of linked claimants, providers and addresses that single-claim models miss. The scale of the problem is large: the Coalition Against Insurance Fraud states that insurance fraud steals at least $308.6 billion every year from American consumers.
Customer retention
Lapse and churn models identify policyholders likely to leave at renewal and suggest the right action, such as a coverage review, a channel change or a service call. These models should be checked for the same fairness issues as pricing models when they change what a customer pays.
How is agentic AI changing insurance claims?
Predictive models score a claim; an AI agent can also carry out steps. In a typical agentic claims flow, one agent reads the first notice of loss and attached documents, another checks policy coverage, another runs fraud and severity models, and a coordinating agent prepares a recommendation with its evidence. A human adjuster approves, changes or rejects it. XenonStack describes this pattern for insurers in Agentic AI for Insurance and on its agentic AI for insurance page.
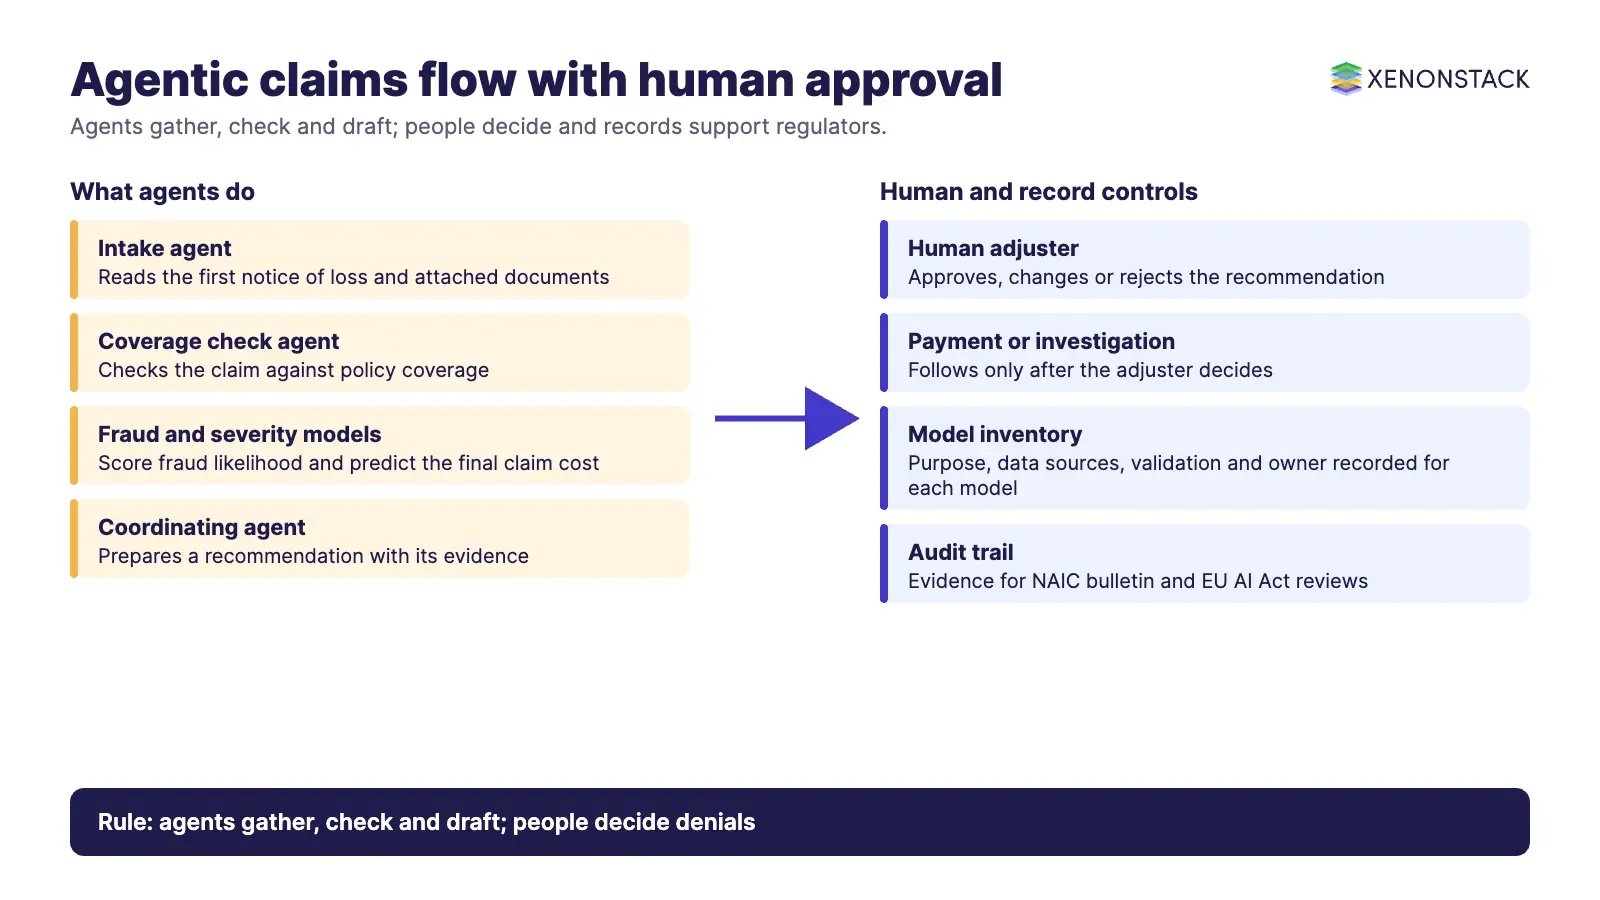
The design question is not whether agents can act, but where a person must stay in the loop. The NAIC bulletin asks insurers to scale controls to the potential harm, considering the type of decision, the degree of human involvement and how explainable the outcome is. A practical rule is that agents gather, check and draft, while people decide on denials, coverage disputes and anything high value. To apply that rule consistently, ElixirData Context OS keeps governed context, versioned policy and decision traces in one decision layer above AI agents.
What regulation applies to insurance analytics and AI?
| Jurisdiction | Instrument | What it requires | Current status |
| European Union | EU AI Act, Regulation (EU) 2024/1689, Annex III point 5(c) | AI systems intended for risk assessment and pricing in relation to natural persons in life and health insurance are high-risk and subject to the high-risk requirements in Chapter III of the Act | The AI Omnibus, Regulation (EU) 2026/1744, sets 2 December 2027 as the application date for Annex III high-risk obligations |
| United States | NAIC Model Bulletin: Use of Artificial Intelligence Systems by Insurers | A written AI systems programme, board-level accountability, risk controls, model inventory, validation, drift monitoring and third-party oversight; AI-supported decisions must not be inaccurate, arbitrary, capricious or unfairly discriminatory | Adopted by the NAIC on 4 December 2023; the NAIC adoption map shows 29 jurisdictions adopted as of 3 November 2026, with California, Colorado, New York and Texas listed separately for insurance-specific rules |
| India | IRDAI Information and Cyber Security Guidelines, 2023; IRDAI (Insurance Fraud Monitoring Framework) Guidelines, 2025 | Security controls for insurer data and systems; a fraud monitoring unit independent of internal audit and participation in the Insurance Information Bureau fraud monitoring technology framework | Cyber guidelines dated 24 April 2023; fraud framework effective 1 April 2026, as reported by JSA |
Note that the EU AI Act separately carves out AI used to detect financial fraud from the credit scoring category in Annex III 5(b). Fraud models in insurance still need sound governance, and in the US the NAIC bulletin applies to any AI system used in regulated insurance decisions.
What governance, security and cost controls should be in place?
Model inventory and documentation: record each model's purpose, data sources, technique, thresholds, validation results and owner. The NAIC bulletin says insurers can expect regulators to ask for these during investigations and market conduct actions. The ElixirData Audit Agent assembles decision lineage, policies and approvals for full compliance traceability when such a request arrives.
Bias and fairness testing: test inputs and outcomes for unfair discrimination before release and after each retraining.
Drift monitoring: watch model performance over time and retire or retrain models that degrade.
Third-party oversight: include audit rights and cooperation with regulators in contracts for external data and models.
Data protection: apply data minimisation, purpose limitation and access controls, and align with GDPR in Europe and IRDAI cyber security guidelines in India.
Cost control: start with use cases that reuse existing data, track compute and data costs per model, and avoid running agents on decisions a rule can make.
In what order should insurers adopt analytics and AI?
Unify the data: join policy, claims, billing and customer data on one governed platform with clear lineage.
Fix reporting: agree loss ratio, claims cycle time and retention metrics across finance, actuarial and operations.
Deploy predictive models: begin with fraud scoring and claims triage, where outcomes are measurable and a person reviews results.
Set up the AI governance programme: inventory, validation, fairness tests and documentation, mapped to the NAIC bulletin and, for EU life and health business, to AI Act high-risk duties.
Add agents with human approval: let agents gather evidence and draft decisions; keep people on denials and high-value claims.
Extend to underwriting and pricing: only once governance is proven, because these are the most regulated decisions. Agentic analytics can then help analysts explore results faster.
What are the trade-offs, and when should you not automate?
| Choice | Benefit | Trade-off |
| More external data in underwriting | Finer risk segmentation | Higher fairness risk and more vendor oversight work |
| Complex models over simple ones | Better predictive accuracy | Harder to explain to customers and regulators |
| Straight-through claims payment | Faster settlement and lower handling cost | Fraud leakage if thresholds are too generous |
| Autonomous agents | Less manual work across steps | Errors compound across steps; needs approval points and audit trails |
Do not automate a decision when data quality is poor, when you cannot explain the outcome to the customer, or when the decision denies cover or a claim without human review. In those cases use analytics to support the adjuster or underwriter, not to replace them. Where agents draft the decision, the ElixirData Approval Agent approves requests within policy boundaries and escalates exceptions with full context.
To map one claims or underwriting decision your agents should make, and the context and policy it depends on, book a Context Workshop. See what happens in the workshop.
Related on XenonStack
- Risk and compliance AI agents: control monitoring and evidence.
- Agentic AI in banking and finance: use cases and benefits.
- AI in banking: agents with every decision on the record.
What should you plan for in 2027?
For insurers, the main dated item for 2027 is the EU AI Act.
- 2 December 2027: the European Commission states that the high risk rules for Annex III use cases apply from this date, after the AI Omnibus extended it (European Commission AI Act page). Insurers with EU life and health business should map risk assessment and pricing models to Annex III and build documentation and human oversight before then.
- 2 August 2028: the same page gives this date for high risk AI embedded in regulated products.
US insurers should keep working to the NAIC bulletin controls already in place.
Frequently asked questions
What is data analytics in insurance?
It is the use of policy, claims, customer and external data to price risk, settle claims, detect fraud and retain customers, moving from descriptive reports to predictive models and AI agents.
Is insurance pricing AI high-risk under the EU AI Act?
Yes for life and health insurance. Annex III point 5(c) lists AI intended for risk assessment and pricing in relation to natural persons in life and health insurance as high-risk. The AI Omnibus sets 2 December 2027 as the application date for these obligations.
What is the NAIC model bulletin on AI?
It is guidance adopted by the NAIC on 4 December 2023 asking insurers to keep a written AI systems programme with governance, risk controls and third-party oversight. The NAIC adoption map shows 29 jurisdictions adopted as of 3 November 2026.
How does agentic AI help insurance claims?
Agents can read documents, check coverage, run fraud and severity models and draft a recommendation, while a human adjuster approves the decision, especially for denials and high-value claims.
Where should an insurer start?
Unify the data, then start with fraud scoring and claims triage, set up AI governance, and only then extend to underwriting and pricing.
Follow XenonStack on LinkedIn: XenonStack on LinkedIn for new guides on agentic AI, data and platform engineering.
Ready to put AI agents to work? Explore ElixirClaw, the agentic OS platform to build, orchestrate and govern AI agents.
Explore the XenonStack platform family: ElixirData · ElixirClaw · ElixirHub · NexaStack · MetaSecure · Neural AI · AgentGRC · AgentSRE · AgentAnalyst · AgentInstruct · AgentRAI · AgentScrum · AgentSearch · AgentForce · AI Aviator · SAIF Aviator · CohortIQ · XenonStack AI · XenonStack UAE